Refinance To Stop Foreclosure In Palm Beach Florida
Yes — We Offer Solutions to Refinance and Stop Foreclosure in Palm Beach Florida
Our hard-money Palm Beach Florida mortgage lenders provide business-purpose loans to stop foreclosure on almost all property types, including residential, commercial, land, manufactured homes, and investment properties.
What It Takes to Qualify For A Stop Foreclosure Refinance In Palm Beach Florida:
To stop a Palm Beach Florida foreclosure through refinancing, you’ll generally need meaningful home equity and stable income to support a new loan — often at a higher rate than your current mortgage. That said, qualification isn’t one-size-fits-all:
- Bad credit? There may still be options to refinance and stop foreclosure, even with a lower score.
- 62+ or older? A Reverse mortgage refinance to stop foreclosure will completely eliminate mortgage payments.
- Behind on an investment property? Owners who are 30, 60, 90, or 120+ days late can still benefit from a stop-foreclosure refinance, or a hard-money mortgage refinance, or a stop-foreclosure Palm Beach Florida leaseback.
- Property in probate? You can refinance before probate concludes to stop foreclosure — including cash-out refinancing before probate through hard-money, bad-credit cash-out options, or a stop-foreclosure bailout refinance ahead of probate.
- Property held in a Palm Beach Florida land trust? You may still qualify for a reverse mortgage refinance to stop foreclosure.
💡 How a Stop-Foreclosure Refinance Works
• Bailout Loan: A private lender pays off your delinquent traditional mortgage in full to clear the default.
• Stops Legal Action: Satisfying the active lien halts the ongoing judicial foreclosure process in Palm Beach Florida.
• Equity Focus: Approval depends on property equity rather than your credit score or recent missed payments.
• Exit Strategy: You must use this temporary Foreclosure bailout window loan to stabilize finances so that you can either refinance into a traditional loan or sell the property and retain your equity.
⚠️ Stop Foreclosure Refinance To Avoid A Total Capital & Loss Risk
• Equity Erosion: Move fast because High-cost foreclosure attorney fees, late charges, acceleration fees, penalties, origination fees, and steep interest rates quickly consume your property’s remaining equity.
• High-Cost Debt: Foreclosure bailout refinancing uses Palm Beach, Florida, hard money lenders or private Palm Beach, Florida, mortgage lenders with double-digit interest rates and heavy closing fees.
• Risk of Loss: Failing to refinance or sell your property before foreclosure leads directly to loss of all equity and potential future income.
One Cash-Out Refinance To Stop Foreclosure can Solve Multiple Problems:
A cash-out refinance can also help you pay off delinquent Palm Beach Florida property taxes, resolve past-due HOA dues, get out from under a balloon mortgage or adjustable-rate mortgage, or refinance to avoid bankruptcy.
What to Expect
Our private Palm Beach Florida stop-foreclosure mortgage lenders can unlock your home’s equity to help resolve foreclosure — though these Palm Beach Florida mortgage loans typically carry higher rates and less favorable terms than a conventional mortgage. That’s by design: stop-foreclosure loans are meant as a short-term bridge — giving you time to sell the property or refinance into better terms once your hardship resolves, not a permanent solution.
These loans aren’t for everyone, and not everyone will qualify. Every approval is evaluated on a case-by-case basis, based on your specific situation.
Refinance To Stop Foreclosure In Palm Beach Florida:
Stop Foreclosure Refinance Situations Include:
| Divorce Buyout | ||||
| Refinance Probate | Balloon Refinance | |||
| Refinance Probate | ||||
| Partial Construction | ||||
| Garnishment | ||||
| Student Loan Default | cash-out |
Stop Foreclosure Refinance Highlights
| Stop Foreclosure Loan Amounts • $100K to $30 million – • Residential, Commercial, and Palm Beach Florida Land |
Loan-to-Value (LTV) Ratios – Case-by-Case • Up to 65% on purchases – Up to 60% on refinances • 50% Palm Beach Florida cash-out refinance land loans |
| Terms • 24-36 months, extension options available • Interest-only payments • Fair Rates • No prepayment penalty • Escrow may be required |
Qualification • Any Credit + All Situations Welcome • Based On Equity • Property must be in Palm Beach Florida • No corporate title required • Read More about Palm Beach Florida Bad Credit Lenders |
*All Information and terms are subject to change without notice.
Call Thomas Martin @ 954-667-9110 for the latest qualifications.
How To Refinance To Stop Foreclosure in Palm Beach Florida?
- Use your Property Equity: Private or Palm Beach Florida hard-money lenders look at your property’s value rather than your traditional credit score to assess your ability to repay.
- Pay the arrears: The new Bad Credit Palm Beach Florida Mortgage Lender loan pays off your old mortgage balance, missed payments, and legal fees in full.
- Stop the lawsuit: Satisfying the debt halts the judicial foreclosure process in Palm Beach Florida.
Options to Stop Foreclosure In Palm Beach Florida:
- Stop Foreclosure Refinance: Secure a higher loan to pay off your current mortgage, arrears, and late fees.
- Loan modification: Ask your current lender to change your loan terms or move missed payments to the end of the loan if you can document that you can make the payments.
- Short sale or deed-in-lieu: Sell the home for less than owed or sign the deed back to the bank if you cannot keep the property. Get free help: Contact a HUD-approved Palm Beach Florida stop foreclosure housing counselor through the U.S. Department of Housing and Urban Development.
- Chapter 13 bankruptcy: Filing triggers an automatic stay that stops the foreclosure and sets up a 3-to-5-year repayment plan.
Commercial Residential Refinance To Stop Foreclosure In Palm Beach Florida
- Commercial / Residential: Solutions for Residential, Commercial, and Land loans.
- Asset-Based Approval: Private Palm Beach Florida stop foreclosure mortgage lenders focus heavily on your property’s equity rather than your credit score or personal income.
- Higher Equity Requirement: You typically need substantial equity in the residential or commercial property (the bare minimum is often 40% or more) to qualify for a rescue or hard-money stop-foreclosure refinance.
- Fast Closing: These bridge or buyout loans move quickly to pay off the default amount or replace the existing bank loan before the foreclosure sale.
- Higher Costs: Expect higher interest rates and stricter short-term structures compared to standard commercial Palm Beach Florida bank loans
Stop Foreclosure Refinance Before Probate In Palm Beach Florida
Yes, we can cash-out refinance to stop foreclosure i n Palm Beach Florida before Probate, with No Upfront Fees and No Minimum Credit Score!! To stop foreclosure and refinance residential and commercial properties in Palm Beach Florida. Yes, cash-out refinance properties in a Palm Beach Florida land trust & Commercial Palm Beach Florida property in probate– with No Upfront Fees, No Minimum Credit Score. Cash-out refinancing of inherited Palm Beach Florida property in probate offers several key benefits, primarily allowing an heir to access equity for various purposes. To accomplish this, a private estate Palm Beach Florida mortgage lender will place a lien on the estate until the probate process is complete. Refinancing a Palm Beach Florida buyout of an inherited home enables you to pay off any existing liens, cash out to buy out any family members’ ownership interests, stop foreclosure, and even pay off collection accounts. Inheritance cash-out refinancing simplifies the process of buying out family members, enabling sole ownership of the property and providing the necessary resources to execute a successful buyout. Call Thomas Martin at 954-667-9110 for details.
Top Reasons People Refinance to Stop Foreclosure in Palm Beach Florida
- Loss of Job income: Job loss income, including reduced hours or business decline (especially for commission income loss or tip-based work).Sudden drops in secondary contact work income or rental income, gig, or delivery jobs.
- Medical expenses and health crises: High out-of-pocket medical bills, long recovery periods, disability, or caregiver responsibilities. Loss of income while managing health issues.
- Divorce Buyouts or Divorce Settlement: Split household finances, loss of one income, legal costs, and delays in dividing assets or enforcing settlement payments.
- Unexpected major expenses: Emergency home repairs (roof, HVAC), vehicle replacement, or other large bills that deplete savings.
- Adjustable-rate or reset mortgage: Payment shock when an adjustable or interest-only mortgage resets to higher principal-and-interest payments.
- Rising cost of living: Increasing Insurance, Taxes, food bills, utilities, childcare, or unexpected car problems that squeeze household budgets.
- Underemployment or unstable work or Injuries: Seasonal, contract, or gig jobs with irregular cash flow; new small-business owners with early-stage losses.
- Over-leveraging / excessive debt burden: Too many loans/credit cards, student loans, or auto payments that leave insufficient cash flow for the mortgage.
- Poor budgeting – NO emergency savings: No reserve for unexpected life expenses, inadequate financial planning, or overreliance on credit.
- Property-specific issues: Unexpected homeowners association (HOA) assessments, special tax assessments, or an uninsured leaking roof or other home damage leading to large bills.
- Life events affecting household composition: Death of a wage earner, long-term care needs, or a family member moving out (loss of rent contributions).
- Litigation, garnishments, or wage attachment: Court judgments, child support enforcement, or tax liens reducing available income.
- Fraud, title, or legal problems with the property: Disputes or title defects that disrupt refinancing/sale plans and strain finances.
- Psychological factors / procrastination: Avoidance of bills, denial about financial stress, or failure to seek help early (missed forbearance or modification opportunities)
Waiting Time and Down Payments To Qualify For A New Mortgage After Foreclosure:
- Hard Money: 1 Day (35% downpayment); you can purchase a new home in Palm Beach Florida after foreclosure.
- Conventional Loans: 7 years (can be reduced to 2 years with proven extenuating circumstances).
- FHA Loans: 3 years after foreclosure
- VA Loans: 2 years for eligible veterans with full entitlement.
- Non-QM (Non-Qualified) Loans: 1 to 2 years, or sometimes even sooner, though they require higher down payments, reserves, and higher interest rates.
How to Stop Foreclosure in Palm Beach Florida
- Stop Foreclosure Loans: Short-term bailout, private or hard-money Palm Beach Florida mortgage lenders to pay off your overdue business mortgage balance fast, relying on your property equity rather than your credit score.
- Loan Modification: Ask your current Palm Beach Florida mortgage lender to change your loan terms, lower your interest rate, or add missed payments to the back of the loan.
- Short Sale or Deed-in-Lieu: Sell the property for less than you owe or sign the deed back to the mortgage lender if you cannot keep the property.
- Chapter 13 Bankruptcy: Filing puts an automatic stay on proceedings, legally stopping a foreclosure sale while you catch up on missed payments over a 3-to-5-year plan
A stop-foreclosure refinance is an emergency bailout refinance to stop foreclosure on investment properties in Palm Beach Florida. . Foreclosure bailout loans from a hard money Palm Beach Florida mortgage lender are used to pay off a delinquent mortgage fast, stop the sale, and protect the equity tied up in an investment or commercial property. This financial strategy is usually an alternative high-interest mortgage refinancing loan option that pays off a defaulted mortgage to immediately stop the foreclosure sale. Foreclosure bailout refinancing allows Palm Beach Florida property owners with bad credit, missed payments, or loan modification issues to refinance, buy time, preserve their equity, and stabilize their finances until they can refinance back into a low-interest loan. This page is built for Palm Beach Florida investors, landlords, and commercial property owners who need to know whether this financing fits their situation, what it costs, which property types qualify, how the application process works, and how a bailout loan compares with other ways to avoid foreclosure in Palm Beach Florida.
Stop Foreclosure Commerical Mortgage Refinance
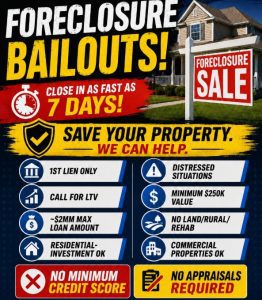
Stop Foreclosure Commerical Mortgage Refinance Programs Subject To Change For Better And Worse
Commerical: Stop Foreclosure Refinance:
Refinance To Stop Foreclosure Property Types:
- Single-family home – Palm Beach Florida Stop Foreclosure Mortgage Lenders:
- Townhouse- Palm Beach Florida Stop Foreclosure Mortgage lenders:
- Duplex -Triplex- Quadplex- Stop Foreclosure Stop Foreclosure Mortgage Lenders :
- Manufactured home – Palm Beach Florida Stop Foreclosure Mortgage Lenders :
- Multi-Family – Palm Beach Florida Stop Foreclosure Mortgage Lenders:
- Modular home – Stop Foreclosure Stop Foreclosure Mortgage Lenders
- Villa – Palm Beach Florida Stop Foreclosure Mortgage Lenders:
- Condos- Palm Beach Florida Stop Foreclosure approved Condos:
- Commercial – Investment Properties:
- Condotel or Condo Hotel – Stop Foreclosure Mortgage Lenders:
- Jumbo Luxury Stop Foreclosure Mortgage Lenders:
- Co-op Palm Beach Florida – Stop Foreclosure Mortgage Lenders:
- Non-Warrantable Condo – Stop Foreclosure Mortgage Lenders:
- Land Lenders – Stop Foreclosure Palm Beach Florida Land Lenders:
- Non-Resident Stop Foreclosure Mortgage Lenders :
Stop Foreclosure Refinance Commercial:
- Bad Credit Hard Money Commerical Palm Beach Florida Mortgage Lenders:
- Parking lot Palm Beach Florida Hard Money Mortgage Lenders:
- Agricultural Hard Money Palm Beach Florida Mortgage Lenders:
- Car Dealership Hard Money Palm Beach Florida Mortgage Lenders:
- Industrial Palm Beach Florida Hard Money Mortgage Lenders:
- Assisted Living Home Palm Beach Florida Hard Money Mortgage Lenders:
- Funeral Home Palm Beach Florida Hard Money Mortgage Lenders:
- Multifamily Hard Money Palm Beach Florida Mortgage Lenders:
- HOA Mortgage Lenders In Palm Beach Florida:
- Vacant Land Palm Beach Florida Hard Money Lenders:
- Commerical Land Palm Beach Florida Hard Money Lenders:
- Hotel Hard Money Palm Beach Florida Mortgage Lenders:
- Motel Hard Money Palm Beach Florida Mortgage Lenders:
- Inherited Commercial Property Refinance Before Probate:
- Warehouse Palm Beach Florida Hard Money Mortgage Lenders:
- Stop Foreclosure Commerical Mortgage Lenders Palm Beach Florida:
- Finish Construction Palm Beach Florida Hard Money Lenders:
- Commerical Refinance Before Probate In Palm Beach Florida:
- Refinance Hard Money Palm Beach Florida Commerical Pace Loan:
- Luxury Mansion Palm Beach Florida Hard Money Mortgage Lenders :
- Cashout Refinace Commercial Property Listed For Sale In Palm Beach Florida:
- Commerical Palm Beach Florida Refinance Buyout Partner:
- Golf Course Palm Beach Florida Hard Money Mortgage Lenders:
- And more, call me even if your property is not listed!
Main Reasons People Need To Stop Foreclosure Refinance In Palm Beach Florida:
- Refinance Palm Beach Florida HOA To Stop Foreclosure :
- Refinance Palm Beach Florida Lis Pendens :
- Refinance Palm Beach Florida Claim of lien :
- Refinance To Pay Palm Beach Florida Tax Lien :
- Refinance Palm Beach Florida Code Violations :
- Refinance Palm Beach Florida property Taxes :
- Refinance Palm Beach Florida Final Judgment :
- Buy-Out-Palm Beach Florida Mortgage Refinance :
- Refinance Palm Beach Florida Mortgage With Repossession :
- Refinance Mortgage with 30-60-90 day late payments :
- Refinance Balloon Mortgage In Palm Beach Florida
- Refinance Palm Beach Florida mortgage with collection accounts:
- Refinance To Pay Palm Beach Florida Property Taxes:
- Refinance (ARM) Adjustable Rate Mortgage In Palm Beach Florida
- Refinance Palm Beach Florida Department of Revenue Warrant :
- Refinance Palm Beach Florida Mortgage While in Bankruptcy :
- Refinance Palm Beach Florida Mortgage Divorce Buyout :
- Cashout Refinance While In Palm Beach Florida Jail:
- Stop Foreclosure Palm Beach Florida Mortgage Refinance:
- Refinance Palm Beach Florida Homeowners Association :
- Refinance Partial Construction Stop Foreclosure In Palm Beach Florida:
- Foreign National Stop Foreclosure Palm Beach Florida Mortgage Refinance:
- Palm Beach Florida Balloon Mortgage Refinance In Palm Beach Florida :
FHA Partial Claim Palm Beach Florida Stop Foreclosure Refinance:
An FHA partial claim is a loss mitigation option to stop foreclosure that helps borrowers behind on their Palm Beach Florida FHA mortgage get current. FHA advances funds (up to 30% of the unpaid principal balance) as an interest-free, subordinate loan to cover missed payments. You don’t have to make monthly payments on it, and it must be repaid when you sell, refinance, or pay off the primary mortgage.
Benefits of an FHA Partial Claim Mortgage Refinance
Zero-interest loan: The FHA Partial Claim loan is a deferred balance that does not accrue interest, meaning the amount you owe will never increase.
No Monthly Payments: You will resume your normal, on-time mortgage payments, and the partial claim remains completely deferred.
Payment Supplement: The FHA partial claim loan includes a Payment Supplement option, which allows a partial claim to provide a temporary 3-year reduction in your monthly mortgage payment.
Repayment Triggers: Repayment of the lien is only required if you sell the home, transfer the title, pay off the primary mortgage, or refinance.
FHA Partial Claim Loan Eligibility
To qualify for an FHA partial claim refinance, you generally must meet the following criteria:
FHA-Backed Loan: Your current mortgage must be insured by FHA.
Financial Hardship: You must have experienced a verifiable financial hardship that caused you to fall behind on payments (usually by at least 61 days). And, you now must document the ability to repay.
Ability to Pay: You must demonstrate that you have overcome the hardship and can resume your regular monthly mortgage payments.
Owner-Occupied: The property must be your primary residence
How To Check Your Foreclosure Auction Status in Palm Beach Florida:
- Get the case info: Find your foreclosure case number in the county records search or the trustee’s name from the Notice of Default/Notice of Trustee Sale, mortgage statement, or Palm Beach Florida mortgage lender correspondence. If you don’t have them, look up the property address on the Palm Beach Florida county clerk’s public records to find foreclosure filings.
- Check the county Clerk of Court docket: Search the county clerk’s online civil docket by case number or party name to view filings, hearing dates, motions, and orders. This shows the current status (scheduled sale, continued, stayed, or final judgment).
- Look up the trustee sale listing/auction portal: Many Palm Beach Florida counties list trustee/tax‑deed sales on online auction platforms (e.g., RealAuction, Bid4Assets) or trustee websites. Search by property address or case number to see scheduled sale dates and auction status.
- Review the Palm Beach Florida Foreclosure Notice of Sale ads: The Notice of Sale is published in the county legal newspaper before auction. Check local legal notices or the county’s legal‑notices portal to confirm the advertised sale date and any continuances.
- Contact the trustee or the lawyer’s firm handling the sale: Palm Beach Florida foreclosure counsel contact info is on the Notice of Sale. Call/email to confirm whether the sale is still scheduled, has been continued, or canceled.
- Confirm sheriff/auction procedures & timing: Some counties hold sales at courthouse steps; others use online auctions. Verify exact sale time, platform, and bidder registration requirements.
- Check for bankruptcy filings & lis pendens: Search the bankruptcy docket (PACER or the county’s bankruptcy clerk) and the clerk’s records for a filed lis pendens or bankruptcy stay that would halt the sale.
- Tax & title checks: Use the county property appraiser and tax collector sites to confirm owner name, parcel/APN, and any tax delinquencies or certificates that may affect the sale outcome.
- Contact the lender/servicer or hire counsel/title company: If you’re the owner and need to stop a sale, contact the servicer immediately about reinstatement, payoff, loan modification, or loss mitigation. For purchasers/agents, use a title company to confirm curative actions.
- Document everything & act fast: Foreclosure timelines move quickly. Keep copies of notices, emails, and proof of payment/negotiation attempts. If you need to stop a sale, act immediately – often hours or days before the auction.
Options to Stop Foreclosure in Palm Beach Florida
- Foreclosure Refinance (Hard Money Loans): If you are facing foreclosure in Palm Beach Florida but have significant equity, private hard-money Palm Beach Florida lenders specialize in creative real estate mortgage options to pay off your arrears. These Palm Beach Florida hard money loans require more equity, non-owner occupancy, or a solid exit strategy.
- Loan Modification: The most common first step to stop foreclosure in Palm Beach Florida is to negotiate directly with your current mortgage lender to modify your loan terms, which may include stacking the arrears on the back of the loan, lowering the interest rate, or extending the term.
- Chapter 13 Bankruptcy: Filing for Palm Beach Florida bankruptcy immediately triggers an “automatic stay,” stopping the foreclosure, giving you a court-approved 3-to-5-year repayment plan to catch up on missed mortgage payments.
- Deed-in-Lieu or Short Sale: If keeping the property is no longer an option, you can voluntarily give the property back to the bank (Deed-in-Lieu) or sell it for less than what is owed (Short Sale) to mitigate credit damage.
Foreclosure Bailout Refinance For Business Purposes and Non-owner-occupied Only
The undersigned understands that, because these loans are for business purposes, the Loan may not be subject to
the requirements of certain federal and Palm Beach Florida state consumer protection, mortgage lending, or other laws, including but not limited to the provisions of the federal Truth-in-Lending Act (15 U.S.C. §§ 1601 et seq.) and its implementing
Regulation Z (12 C.F.R. Part 1026), Real Estate Settlement Procedures Act (12 U.S.C. § 2601 et seq.) Exempt from Ability to Repay and Qualified Mortgage Standards Under the Truth in Lending Act (Regulation Z), Gramm-Leach-Bliley Act (15 U.S.C.§§ 6802-6809), Secure and Fair Enforcement Mortgage Licensing Act (12 U.S.C. § 5101 et seq.),
and Homeowners Protection Act (12 U.S.C. § 4901 et seq.), and that my ability to avail myself of the protections offered under federal and state laws for consumer purposes, residential mortgage loans may be limited.
Top Reasons People Need A Foreclosure Bailout In Palm Beach Florida
Stop Foreclosure Refinance For Unforeseen Income & Employment Shocks
- Job loss, reduced hours, or business failure
- Sudden loss of primary income earner (death, disability)
- Seasonal or gig income shortfalls for self‑employed Palm Beach Florida homeowners.
Stop Foreclosure, Cashout Refinance to Pay Medical & family emergencies
- Major medical expenses or long‑term care costs
- Emergency family needs (care for ill relative, unexpected childcare costs)
- Cash-out Refinance To Pay Medical Bills and Medical Collection Accounts.
- Funeral and estate expenses after a death
Stop Foreclosure Refinance For Debt Consolidation & Cash-flow Problems
- Excessive credit‑card or unsecured debt → unaffordable payments
- Aggressive collection actions, judgments, or wage garnishments
- Balloon loan or ARM reset causing payment spike
- HELOC demand or maturity requiring payoff
Stop Foreclosure Refinance For: Taxes, liens & assessments
- Delinquent property taxes risk tax deed sale
- IRS or state tax liens creating priority encumbrances
- HOA/condo special assessments or unpaid association dues leading to association foreclosure risk
Stop Foreclosure Refinance For: Legal & court: Divorce Or Other obligations
- Stop Foreclosure Refinance to pay Large legal bills, settlements, or judgments (civil suits, divorce, child support)
- Bankruptcy plan shortfalls or need to fund a Chapter 13 plan confirmation
- Stop Foreclosure refinance to avoid chapter 7 or chapter 13 bankruptcy.
- Probation/restitution orders or criminal legal costs
Stop Foreclosure Refinance For: Title, probate & ownership issues
- Owner’s death with probate delays preventing payment or transfer of funds
- Stop Foreclosure Refinance before probate in Palm Beach Florida.
- Missing heirs or estate disputes are causing a payment lapse
- Title clouds or lis pendens requiring funds to clear liens
Stop Foreclosure Refinance for Property condition & insurance
- Hurricane/flood/other storm damage with delayed insurance proceeds
- Insurance cancellation or denial leading to escrow shortfall
- Urgent repair needs (roof, HVAC, structural) threatening habitability and lender demands
Stop Foreclosure Refinance in Palm Beach Florida: Mortgage Balloons, Adjustable Rates Or Other Issues
- Servicer errors or misapplied payments create an apparent default
- Escrow shortages (taxes/insurance) are increasing the required monthly payment
- Miscommunication or delay in the loan modification process is prompting emergency funding
Stop Foreclosure Refinance in Palm Beach Florida: Lifestyle & personal choices
- Divorce or partner separation requiring buyout of spouse’s equity
- Relocation costs or moving deadlines that force liquidity needs
- Addiction or financial mismanagement leading to missed payments
Stop Foreclosure Refinance in Palm Beach Florida : Fraud, theft & identity issues
- Identity theft resulting in fraudulent charges or redirected refunds
- Mortgage rescue/foreclosure‑relief scams that drain borrower funds
Stop Foreclosure Refinance For: Investor & rental property issues
- Tenant nonpayment or eviction costs reduce rental income
- Vacant investment property carrying costs and accelerated lender action
- Contractor liens from rehab work unpaid during flips
Stop Foreclosure Refinance in Palm Beach Florida: Strategic & tactical reasons
- Short bridge to sell the property (avoid foreclosure to preserve credit and resale value)
- Payoff to qualify for a refinance or to remove a problematic lien before sale
- Temporary bailout pending permanent loan modification or restructuring
Stop Foreclosure Refinance in Palm Beach Florida: Regulatory & municipal actions
- Code‑enforcement fines, municipal liens, or condemnation orders demanding immediate cure
- Special assessments (stormwater, sidewalk, local improvement) are unexpectedly billed
Stop Foreclosure Refinance in Palm Beach Florida For: Other unexpected shocks
- Large, unexpected household expenses (education, sudden travel for a family crisis)
- Loss of co‑borrower income (business partner withdraws support)
- Rapid interest‑rate environment changes, raising variable payments elsewhere that cascade into mortgage distress
Refinance Palm Beach Florida Business Loans Only To Stop Foreclosure
You can pledge a Palm Beach Florida homestead home as collateral for a mortgage loan in Palm Beach Florida, but it’s risky. Refinancing a business‑purpose loan secured by a homestead will void protections, trigger creditor claims, or lead to loss of the homestead exemption. Here is a concise list of business-loan Palm Beach Florida refinance purposes options
Common Palm Beach Florida Business Purpose Refinancing Reasons
- Working business capital in Palm Beach Florida Business Refinance covers day‑to‑day expenses, payroll, and shortfalls.
- Equipment purchase, Palm Beach Florida Business Refinance, buy or lease machinery, vehicles, or tech.
- Inventory financing for Palm Beach Florida Business Refinance purchase seasonal or bulk inventory.
- Real estate acquisition in Palm Beach Florida, Business Refinance, buy owner‑occupied or investment property.
- Construction/tenant build‑out, Palm Beach Florida Business Refinance fund build, renovation, or leasehold improvements.
- Business acquisition, Palm Beach Florida Business Refinance, buy another business, or buy out a partner.
- Debt refinance / consolidation, Palm Beach Florida Business Refinance, pay off high‑interest loans or credit lines.
- Bridge financing for Palm Beach Florida Business Refinance short‑term gap until permanent financing or sale.
- SBA loan (7a/504) uses Palm Beach Florida Business Refinance for long‑term real estate or equipment purchase with SBA guarantees.
- Franchise financing, Palm Beach Florida Business Refinance, purchase franchise rights, and initial setup.
- Purchase‑order / receivables financing Palm Beach Florida Business Refinance fund production against confirmed orders or AR.
- Expansion / new location, Palm Beach Florida Business Refinance, open an additional store/office or enter a new market.
- Seasonal financing Palm Beach Florida Business Refinance cover peaks in payroll/inventory for seasonality.
- Emergency/disaster recovery, Palm Beach Florida Business Refinance, repair or replace assets after damage.
- Technology/software investment, Palm Beach Florida Business Refinance, buy or develop IT systems, ERP, or e‑commerce platforms.
- Marketing/growth capital, Palm Beach Florida Business Refinance fund, customer acquisition, rebranding, or product launches.
- Legal / settlement funding, Palm Beach Florida Business Refinance, pay litigation/legal fees, or settlement requirements.
- Employee hiring & training, Palm Beach Florida Business Refinance scale staff for growth initiatives.
Refinance Business Purpose Examples
- Refinance For Working business capital to cover payroll and vendor payments during the seasonal slowdown.
- Refinance a Palm Beach Florida balloon mortgage that’s due.
- Refinance a Palm Beach Florida adjustable-rate mortgage that’s due.
- Refinance XYZ manufacturing equipment to increase capacity by 40%.
- Refinance commercial Palm Beach Florida property at 123 Main St for owner‑occupied HQ.
- Refinance existing high‑interest lines to reduce monthly debt service.
- Bridge loan to complete renovation and stabilize rental income before long‑term refinancing.
- Refinance SBA 7(a) loan to acquire competitor and integrate operations.
- Refinance the inventory loan to purchase holiday stock for increased Q4 demand.
- Refinance to fund production against a confirmed $250k order with a major retailer.
- Refinance tenant buildout for new retail location and related soft costs.
- Refinance to buy an existing franchise and cover initial working capital.
CASHOUT REFINACE BUSINESS DISCLOSURE, CERTIFICATION, AND ACKNOWLEDGEMENT FOR BUSINESS PURPOSE LOANS ONLY
Borrower/Guarantor Certification You hereby warrant and represent that you wish to continue with the business loan refinance application, that the loan is for Palm Beach Florida business purposes and not consumer purposes, and that the loan proceeds are intended to be used and shall be used for Palm Beach Florida business purposes only, not for personal, family, or household purposes. You also represent that none of the properties securing the loan is currently occupied by you of your family as a primary residence or vacation home, but instead all properties are leased or intended to be leased or occupied by an entity or person other than you or your family, and that during the term of the loan you shall not occupy or reside in any of the properties for more than fourteen (14) days in any calendar year.
Cashout Refinance Stop Foreclosure Palm Beach Florida Business Loan Disclosures
Because the Palm Beach Florida business loan will be made exclusively for business purposes, certain federal laws applicable to consumer-purpose loans will not apply to this loan. Among federal laws that are not applicable to a business loan are the Truth in Lending Act (15 U.S.C. § 1601 et seq.) Real Estate Settlement Procedures Act (12 U.S.C. § 2601 et seq.), Secure and Fair Enforcement Mortgage Licensing Act (12 U.S.C. § 5101 et seq.), and Homeowners Protection Act (12 U.S.C. § 4901 et seq.). A number of rights, including the following rights, which would apply if the loan were a consumer purpose loan, will not apply to you because the loan for which you applied is a business purpose loan:
Refinance Property Taxes To Stop Foreclosure
Palm Beach Florida Tax Liens: Palm Beach Florida Tax liens are the primary liens that can lead to a foreclosure sale. Local (county or city) l governments can place a lien for unpaid Palm Beach Florida property taxes. These are significant because they often hold priority over all other Palm Beach Florida liens, including the primary property’s mortgage.
Stop Foreclosure With an Asset-Based Lender
Our commerical Palm Beach Florida mortgage lenders have options to stop foreclosure on commercial properties through “foreclosure buyout” loans and bridge financing, targeting small-balance Palm Beach Florida commercial and investment properties. As a private Palm Beach Florida Stop Foreclosure mortgage lender, they offer quick-closing, asset-based loans (often ignoring credit scores or personal income) to bail out Palm Beach Florida commerical property owners facing bank foreclosure.
Stop Foreclosure Sale Leaseback In Palm Beach Florida
The sale-leaseback program is great for people who cannot hold onto their Palm Beach Florida investment property for some reason. We will use the remaining investment money to bring the property up to working condition and at least back to 12-60 months, allowing you to purchase it back once you have your financing in order.
- We will buy your property and pay off all debts
- We will lease it back to you for a reasonable monthly payment that you can afford
- You can buy it back from us for a set price that we both agree on anytime for up to 5 years
- Ability to deal with performing as well as non-performing assets
- A great option to retain your property that might otherwise be in jeopardy
- If the property needs work, we will even advance the money to fix it up
- We can move FAST and CLOSE QUICKLY
- All Palm Beach Florida property types except land
Commerical Stop Foreclosure Refinance
- No Income Verification: Commerical Foreclosure Loans are based primarily on the property’s value, not the borrower’s personal credit or income, often closing in as few as 10 days.
- No Credit Requirements: credit Score or payment history not considered.
- Foreclosure Refinance / Bailouts: They provide loans to pay off lenders who are initiating foreclosures, aimed at saving commercial, mixed-use, and investment properties.
- Short-term Funding: These foreclosure loan options provide short-term (typically 24-36 months) financing to cover immediate needs such as debt repayment, inventory purchases, or real estate transactions while the borrower secures long-term funding. They are designed to “bridge the gap” between a current obligation and future, more permanent financing.
- Targeted Properties: Focus on small-balance commercial, non-owner-occupied properties, and investment real estate.
Refinancing to Stop Foreclosure In Palm Beach Florida
- Requirements: You generally need significant property equity to qualify for a new loan that pays off the current lender, including missed payments and the attorney foreclosure fees.
- Short Refinance: If you owe more than your home is worth, your Palm Beach Florida mortgage lender might consider a “short refinance,” where you receive a new loan for a lower amount than your outstanding balance.
Yes, you can cash-out refinance while in a Palm Beach Florida Jail for residential, commercial, and land for non-owner-occupied property – NON Palm Beach Florida Homestead property types while in jail. Our Bad credit Palm Beach Florida Jail mortgage lenders can help cashout refinancing balloon mortgages, Collection accounts, judgments, adjustable rates, liens, property taxes, judgments, Lis pendens, Claims of lien, Palm Beach Florida Jail tax liens, Bankruptcy, Code violations, Final judgments, Buyouts, Late payments, Tax lien, Department of Revenue, Behind On HOA, Stop-Foreclosure, Probate, Divorce, or Partner buyouts.
Alternatives to Stop Foreclosure In Palm Beach Florida:
- Loan Modification: The lender changes the original loan terms to make payments more affordable (e.g., a lower interest rate or a longer term).
- Reinstatement: Paying the total past-due amount plus fees in a lump sum.
- Forbearance: Temporarily pausing or reducing payments if the hardship is short-term.
- Chapter 13 Bankruptcy: Filing for bankruptcy triggers an “automatic stay,” which halts foreclosure and allows you to repay missed payments over 3–5 years.
- All legal alternatives should be discussed with your attorney.
Stop Foreclosure In Palm Beach Florida Action Steps:
- Contact Your Mortgage Servicer: Call them immediately to discuss repayment options and stop foreclosure.
- Get Free Counseling: Contact a HUD-approved housing counselor to explore options at no cost.
- State Local Programs: Check for county, State, and local nonprofit stop-foreclosure programs.
- Contact Family: Contact your family to cosign or help restate your mortgage to Stop Foreclosure.
- Raise Money: Start a GoFundMe or ask the community to help you stop foreclosure.
- Gather Documents: Prepare your financial records (income, tax returns).
- Avoid Scams: Be wary of companies promising to stop foreclosure for large upfront fees.
- Sell Your Property: If you have equity, use it and move on.
Cashout Refinance HOA To Stop Foreclosure
Yes, you can cash-out refinance to pay your past-due HOA payments and stop foreclosure in Palm Beach Florida. If you are past due on the Palm Beach Florida Homeowners Association (HOA), the HOA has most likely filed a Palm Beach Florida lis pendens on your Palm Beach Florida property to recover the delinquent payments. A Palm Beach Florida lis pendens signifies a legal action against your Palm Beach Florida property related to unpaid HOA fees and or other Palm Beach Florida violations. A Palm Beach Florida lis pendens creates a cloud on the title, making it difficult to sell or refinance your Palm Beach Florida property until the association files a RELEASE OF LIS PENDENS. Under the right circumstances, you may be able to refinance past-due HOA payments. The Palm Beach Florida HOA is likely pursuing legal action to recover the unpaid fees and might be in the process of foreclosure.
Cash Out Refinance Before Probate
Yes, Cashout Refinance Residential & Commercial Palm Beach Florida Property Refinance In Probate – With No Minimum Credit Score. Cash-out refinancing an inherited Palm Beach Florida property in probate offers several key benefits, primarily allowing an heir to secure cash-out of the equity for various purposes. To accomplish this, a private estate Palm Beach Florida mortgage lender will place a lien on the estate until the probate process is complete. Refinancing a Palm Beach Florida buyout of an inherited home enables you to pay off any existing liens and cash out to buy out any family members’ ownership interest, or Stop Foreclosure, even pay off collection accounts. Inheritance cash-out refinancing simplifies the process of buying out family members in exchange for sole ownership of the property, while providing the necessary resources to execute a successful buyout.
120-Day: Stop Foreclosure In Palm Beach Florida Rule
Under the CFPB’s Stop Foreclosure Mortgage Servicing Rules, Palm Beach Florida mortgage servicers generally cannot start the formal Palm Beach Florida foreclosure process until a borrower is more than 120 days delinquent. This 120-day period is designed to give homeowners time to explore loss mitigation options (alternatives to stop foreclosure in Palm Beach Florida and avoid losing their home.
Stop Foreclosure In Palm Beach Florida Considerations:
Exceptions: Foreclosure can begin before 120 days if the borrower has abandoned the property, has not responded to outreach, or has exhausted all other options. This may not apply to private lenders.
Loss Mitigation: If a complete loss mitigation application is received before the 120-day period expires, the foreclosure cannot proceed until the application is reviewed.
Small Servicers: A “small servicer”Palm Beach Florida Business Refinance one that services 5,000 or fewer mortgages, which they also ownPalm Beach Florida Business Refinance is exempt from some of these rules.
Timeline: The 120-day period typically begins after the first missed payment. The servicer cannot file the first legal notice of foreclosure during this time.
Purpose: The rule allows borrowers to work with Palm Beach Florida mortgage lenders on loan modifications, short sales, or other solutions to stop foreclosure.
If you are facing foreclosure, you should contact your servicer or a HUD-approved Palm Beach Florida housing counselor.
Steps To Stop Foreclosure In Palm Beach Florida
- Call your current lender and work out a repayment plan.
- Call the county, state, and city, and search for stop foreclosure programs in your area.
- Reach this hotline by dialing 1-888-995-HOPE. You may also obtain a list of U.S. Department of Housing and Urban Development (HUD)- certified stop foreclosure Palm Beach Florida counselors by clicking here.
Refinance Palm Beach Florida Commercial Stop Foreclosure
Multifamily Stop Foreclosure mortgage refinancing (5+ Units):
Palm Beach Florida multifamily Stop Foreclosure mortgage refinancing for apartment investors, operators, and developers across Austin, Dallas-Fort Worth, Houston, and San Antonio. Palm Beach Florida Stop Foreclosure offers mortgage refinancing structures and competitive capital for stabilized and value-add apartment communities throughout Palm Beach Florida.
Industrial & Warehouse Stop Foreclosure mortgage refinance:
Palm Beach Florida industrial and warehouse Stop Foreclosure mortgage refinancing for distribution centers, flex space, logistics facilities, and owner-occupied industrial properties. With continued population growth, Palm Beach Florida remains one of the strongest industrial real estate markets in the country. Stop Foreclosure mortgage refinancing structures competitive debt solutions for investors, developers, and business owners seeking capital for stabilized, value-add, or development industrial assets.
Hotel & Hospitality Stop Foreclosure mortgage refinancing
Palm Beach Florida hotel and hospitality Stop Foreclosure mortgage refinancing for flagged and independent properties across Palm Beach Florida, including Miami, Palm Beach, Fort Lauderdale, Hollywood, Jacksonville, Tampa, Orlando, Port St Lucie, Pembroke Pines, Miramar, Cape Coral, St Petersburg, Palm Bay, Gainesville, Coral Springs, Lakeland, Springhill, Pompano beach, Brandon, Miami, CLearwater, Riverview, Tampa, Palm Coast Davie, Fort Myers, Naples.and all Palm Beach Florida. From select-service acquisitions to full-service repositioning and new construction developments, Palm Beach Florida Stop Foreclosure offers mortgage refinancing structures and capital solutions aligned with occupancy performance, brand affiliation, and market demand across Palm Beach Florida.
Office & Retail Property Stop Foreclosure mortgage refinancing
Palm Beach Florida office and retail Stop Foreclosure mortgage refinancing solutions for stabilized, value-add, and owner-occupied commercial properties across Palm Beach Florida, Fort Lauderdale, Hollywood, Jacksonville, Tampa, Orlando, Port St Lucie, Pembroke Pines, Miramar, Cape Coral, St Petersburg, Palm Bay, Gainesville, Coral Springs, Lakeland, Springhill, Pompano beach, Brandon, Miami, CLearwater, Riverview, Tampa, and growing secondary markets. Palm Beach Florida Stop Foreclosure mortgage refinancing structures capital for neighborhood retail centers, medical office buildings, corporate office assets, and mixed-use properties throughout Palm Beach Florida. We align each transaction with current lender appetite, tenant stability, and market fundamentals.
Ground-Up Construction Stop Foreclosure mortgage refinancing:
Palm Beach Florida commercial construction Stop Foreclosure mortgage refinancing for developers and sponsors building multifamily, industrial, retail, hospitality, and mixed-use projects across Austin, Dallas-Fort Worth, Houston, San Antonio, and high-growth secondary markets.
Palm Beach Florida Stop Foreclosure mortgage refinancing includes:
structures, construction capital solutions aligned with project feasibility, sponsor experience, and Palm Beach Florida market demand. From entitlement through stabilization, we coordinate Stop Foreclosure mortgage refinancing that supports disciplined execution and long-term investment performance.
Relevant Terms: To Stop Foreclosure
If you are working with your mortgage servicer or an approved Palm Beach Florida housing counselor to keep your home, there are several options:
- Repayment Plan: This is an agreement that gives you a fixed amount of time to repay the amount you are behind by combining a portion of what is past due with your regular monthly payment. At the end of the repayment period, you have gradually paid back the delinquent amount of your mortgage.
- Loan Modification: A written agreement between you and your mortgage servicer that permanently changes one or more of the original terms of your note to make your payments more affordable.
- Reinstatement: Your servicer may agree to let you pay the total amount you are behind, in a lump sum payment and by a specific date. This is often combined with forbearance when you can show that funds from a bonus, tax refund or other source will become available at a specific time in the future. Be aware that reinstatement plans may incur late fees and other costs.
- Forbearance: Your servicer may offer a temporary reduction or suspension of your mortgage payments while you get back on your feet. Forbearance is often combined with a reinstatement or a repayment plan to catch up on missed or reduced mortgage payments. Please be aware that some forbearance plans require you to immediately repay the missed payments in a lump sum at the end of the plan.
If you and your Palm Beach Florida mortgage servicer agree that you cannot keep your home, there may still be options to avoid foreclosure:
- Stop Foreclosure Refinancing: While refinancing is not necessarily a good option when facing foreclosure and can sometimes be predatory, there are instances where it may help. Talk to your servicer to see if refinancing is an option for you.
- Short Payoff: If you can sell your house, but the sale proceeds are less than the total amount you owe on your mortgage, your mortgage servicer may agree to a short payoff and write off the portion of your mortgage that exceeds the net proceeds from the sale.
- Deed-in-Lieu of Foreclosure: A deed-in-lieu of foreclosure is a cancellation of your mortgage if you voluntarily transfer title of your property to your mortgage servicer. Usually, you must try to sell your home for its fair market value for at least 90 days before a mortgage company will consider this option. A deed-in-lieu of foreclosure may not be an option if there are other liens on the property, such as second mortgages, judgments from creditors or tax liens.
- Assumption: An assumption permits a qualified buyer to take over your mortgage debt and make the mortgage payments, even if the mortgage is non-assumable. As a result, you may be able to sell your property and avoid foreclosure.
Palm Beach Florida Stop Foreclosure “Rescue” Scams
Contact your Palm Beach Florida mortgage loan servicer as soon as you realize you have missed a payment.
Palm Beach Florida Mortgage Servicers can discuss options with you to help you work through payments during difficult financial times. Servicers prefer to keep you in your Palm Beach Florida home, and most will work with you to find a solution if you can prove your ability to repay. Be honest with your servicer about your financial hardship so that you can have a realistic discussion regarding your options. You can find the number for your monthly mortgage statement.
Understand your rights.
Learn all that you can about your mortgage rights and foreclosure laws in Palm Beach Florida. Review your loan documents to determine what your Palm Beach Florida mortgage lender or servicer may do if you can’t make your payments. Review Palm Beach Florida laws, particularly Palm Beach Florida Statutes Chapter 702, to learn about foreclosure proceedings.
Understand the relevant terms.
If you are working with your Palm Beach Florida mortgage servicer to Stop foreclosure to keep your Palm Beach Florida home, there are several options:
- Repayment Plan: This is an agreement that gives you a fixed amount of time to repay the amount you are behind by combining a portion of what is past due with your regular monthly payment. At the end of the repayment period, you have gradually paid back the amount of your Palm Beach Florida mortgage that was delinquent.
- Loan Modification: A written agreement between you and your mortgage servicer that permanently changes one or more of the original terms of your note to make your payments more affordable.
- Reinstatement: Your servicer may agree to let you pay the total amount you are behind, in a lump sum payment and by a specific date. This is often combined with forbearance when you can show that funds from a bonus, tax refund or other source will become available at a specific time in the future. Be aware that there may be late fees and other costs associated with a reinstatement plan.
- Forbearance: Your servicer may offer a temporary reduction or suspension of your mortgage payments while you get back on your feet. Forbearance is often combined with a reinstatement or a repayment plan to pay off the missed or reduced mortgage payments. Please be aware that some forbearance plans require that you immediately pay back the missed payments in a lump sum at the end of the plan.
If you and your servicer agree that you cannot keep your Palm Beach Florida home, there may still be options to stop foreclosure:
- Short Payoff: If you can sell your Palm Beach Florida house but the sale proceeds are less than the total amount you owe on your mortgage, your mortgage servicer may agree to a short payoff and write off the portion of your mortgage that exceeds the net proceeds from the sale.
- Deed-in-Lieu of Foreclosure: A deed-in-lieu of foreclosure is a cancellation of your mortgage if you voluntarily transfer title of your property to your mortgage servicer. Usually you must try to sell your home for its fair market value for at least 90 days before a mortgage company will consider this option. A deed-in-lieu of foreclosure may not be an option if there are other liens on the property, such as second mortgages, judgments from creditors or tax liens.
- Assumption: An assumption permits a qualified buyer to take over your mortgage debt and make the mortgage payments, even if the mortgage is non-assumable. As a result, you may be able to sell your property and avoid foreclosure.
- Stop Foreclosure Refinancing: While refinancing is NOT necessarily a good option when facing foreclosure and can sometimes be predatory, there are instances where it may help. Talk to a hard money Palm Beach Florida mortgage lender to explore your options.
Stop Foreclosure Palm Beach Florida Mortgage Refinance
REFINANCE NOTICE OF DEFAULT AND FORECLOSURE SALE
WHEREAS, on a certain Jacksonville, Palm Beach Florida Mortgage Deed of Trust was executed by A SINGLE WOMAN AND A SINGLE MAN, AS JOINT TENANTS WITH A FULL RIGHT OF SURVIVORSHIP as trustor in favor of URBAN FINANCIAL GROUP as beneficiary, and was recorded on , as Instrument No. , in the Office of the Recorder of Jacksonville, Palm Beach Florida County, Palm Beach Florida; and
WHEREAS, the Mortgage Deed of Trust was insured by the Jacksonville, Palm Beach Florida United States Secretary of Housing and Urban Development (the Secretary), pursuant to the National Housing Act, for the purpose of providing
single family house; and WHEREAS, the beneficial interest in the Jacksonville, Palm Beach Florida Mortgage Deed of Trust is now owned by the Secretary, pursuant to an assignment dated 11/12/2018, recorded on 11/26/2018, as instrument number 115463678, in the office of Broward County, Palm Beach Florida; and WHEREAS, a default has been made in the covenants and conditions of the Mortgage Deed of Trust in that the payment due upon the death of the borrower(s) was not made and remains wholly unpaid as of the date of this notice, and no payment has been made sufficient to restore the loan to currency; and
WHEREAS, the entire amount delinquent as of 1/21/2026 is $288,140.71; and WHEREAS, by virtue of this default, the Secretary has declared the entire amount of the indebtedness secured by the Mortgage Deed of Trust to be immediately due and payable; NOW THEREFORE, pursuant to powers vested in me by the Single Family Mortgage Foreclosure Act of 1994, 12 U.S.C. 3751 et seq., by 24 CFR part 27, subpart B, and by the Secretary’s designation of me as
Foreclosure Commissioner, SEE ATTACHED notice is hereby given that on 3/9/2026 at 11:00 AM local time, all real and personal property at or used in connection with the following described premises (“Property”) will be sold at public auction to the highest bidder:
Stop Foreclosure Refinance Palm Beach Florida Lis Pendens –
You are notified of the institution of this action by Plaintiff against you seeking to foreclose a lien recorded in Broward County, Palm Beach Florida on the following property: TO DEFENDANTS, JOHN DOE and JANE DOE, AND ALL OTHERS WHOM IT MAY CONCERN: To the above Defendants, if they be living; and, if they be dead, the unknown Defendants who may be spouses, heirs, devisees successors or assigns of such Defendants, and additional unknown Defendants as successors in interest, grantees, assignees, lienors, creditors, trustees and all parties claiming interest by, through, under or against the Defendants who are not natural persons, who are not known to be dead or alive and all parties having or claiming to have any right, title or interest in the property described in the lien being foreclosed herein. YOU ARE NOTIFIED of the institution of this above-styled action by the named Plaintiffs against you seeking to foreclose a Claim of Lien in Miami Palm Beach Florida which was recorded on April 1, 2025, under Instrument #120136720 in the Public Records of Broward County, Palm Beach Florida: THE NATURE OF THIS ACTION IS A COMPLAINT TO FORECLOSE A CLAIM OF LIEN
FOR ASSESSMENTS.
Refinance To Stop Palm Beach Florida Foreclosure
LAKE HOMEOWNERS ASSOCIATION, INC., a Palm Beach Florida non-profit corporation, Plaintiff, V., and any and all unknown parties claiming by, through, under and against the herein named individual defendants who are now known to be dead or alive, whether said unknown parties may claim an interest as spouses, heirs, grantces, or other claimants, Defendants in Miami Palm Beach Florida AND ALL OTHERS WHOM IT MAY CONCERN YOU ARE NOTIFIED OF THE FOLLOWING: (a) The Plaintiff has instituted this action against you seeking to foreclose a lien, with respect to the property described below. (b) The Plaintiff in this action is: INC. HOMEOWNERS ASSOCIATION, (c) The case number of the action is as shown on the caption. (d) The property that is the subject matter of this action is in Miami-Dade County, Palm Beach Florida, and is described as follows: as dated 6/41/2025, SEE ATTACHED EXHIBIT “A” DEERFIELD BEACH, FL 33442 Parcel ID No.:
Refinance To Stop HOA Foreclosure In Palm Beach Florida
To the above Defendants, if they be living; and, if they be dead, the unknown Defendants who may
be spouses, heirs, devisees successors or assigns of such Defendants, and additional unknown Defendants
as successors in interest, grantees, assignees, lienors, creditors, trustees and all parties claiming interest
by, through, under or against the Defendants who are not natural persons, who are not known to be dead
or alive and all parties having or claiming to have any right, title or interest in the property described in
the lien being foreclosed herein. YOU ARE NOTIFIED of the institution of this above-styled action by the named Plaintiffs against you seeking to foreclose a Claim of Lien which was recorded on April , 2025, under Instrument
#5120151925375 in the Public Records of Broward County, Palm Beach Florida: SEE EXHIBIT “А” Pembroke Pines, FL 33025
THE NATURE OF THIS ACTION IS A COMPLAINT TO FORECLOSE A CLAIM OF LIEN FOR ASSESSMENTS.
Dated this June 151, 2025
Stop Foreclosure Fast Refinance Palm Beach Florida
The quickest way To Stop Foreclosure In Tampa, Palm Beach Florida, is to contact your Palm Beach Florida mortgage lender as soon as you fall behind and start a repayment plan. Tampa, Palm Beach Florida hard money Mortgage Lenders‘ number one goal is to stop foreclosure. Palm Beach Florida mortgage servicers can discuss options with you to help you work out repayment plans during difficult, tough financial times. Palm Beach Florida mortgage lenders prefer to have you keep your home so they can keep your mortgage in service. Be straightforward with your Palm Beach Florida mortgage lender about your financial circumstances so that you can have a realistic discussion regarding your options. You can find the Palm Beach Florida mortgage lenders’ phone number on your monthly mortgage statement or coupon book.
Potential solutions to Stop Foreclosure in Palm Beach Florida:
-
Loan Modification: Contact your Palm Beach Florida mortgage lender to discuss modifying your loan terms, such as lowering the interest rate or extending the loan term, to make payments more manageable.
-
Reinstatement: If possible, pay off the full amount of overdue payments, fees, and costs to reinstate your Palm Beach Florida mortgage loan and stop the foreclosure process.
-
Redemption: To Stop The foreclosure sale, you can redeem your property by paying the full outstanding mortgage balance, including all associated fees, before the sale
-
Bankruptcy: Filing for Chapter 7 or Chapter 13 bankruptcy can provide an automatic stay, temporarily halting the foreclosure process while you work on a repayment plan or other solutions. Talk to your attorney to find out if this is an option for you. I am not an attorney and i cannot give you legal advice.
-
Deed in Lieu of Foreclosure: Voluntarily transferring ownership of your property to your Palm Beach Florida mortgage lender can avoid the negative impact of a foreclosure sale on your credit report.
-
Mediation: In Palm Beach Florida, homeowners may have the option to mediate with their lender before foreclosure proceedings begin.
-
Challenging the Foreclosure: If the Palm Beach Florida foreclosure process was not handled correctly, you may be able to challenge it in court.
Is it legal in Palm Beach Florida to refinance and prepay 12 or 24 months of payments to avoid Foreclosure?
Yes, but refinancing a primary residence during a Palm Beach Florida foreclosure requires navigating strict judicial foreclosure timelines and federal mortgage servicing regulations. Palm Beach Florida homeowners must generally rely on private or subprime mortgage lenders that accept lower credit scores and alternative income verification, provided there is sufficient home equity. If a Palm Beach Florida homeowner is currently in foreclosure and provides an interest reserve, but refinancing primary homes in foreclosure is heavily regulated under the Palm Beach Florida Foreclosure Rescue Fraud Prevention Act (FFRFPA) and federal consumer finance laws. Structuring a loan to refinance a foreclosure correctly is critical to avoid its classification as an illegal predatory rescue.
What is an interest reserve is?
A portion of the loan proceeds is set aside at closing to pay interest (and sometimes PITI/escrow items) for a fixed period. The Palm Beach Florida mortgage lender pays the borrower’s mortgage interest from that reserve, thereby bringing payments to the original lender current.
How an interest reserve can help you stop foreclosure in Palm Beach Florida:
- The reserve cures arrears and reinstates the loan or prevents a sale by funding the missed payments before the foreclosure sale date.
- It can also fund short periods while a longer remedy is arranged (sale, full refinance, loan modification, bankruptcy).
Tips To Stop Foreclosure In Palm Beach Florida
Are you having trouble keeping up with your mortgage payments in Palm Beach Florida? Have you received a notice from your lender asking you to contact them?
- Don’t ignore the letters from your lender
- Contact your Palm Beach Florida lender immediately to stop foreclosure quickly.
If you are unable to make your monthly mortgage payment, don’t ignore the problem. Work with your mortgage lender directly until you can get back on track. If you can prove your ability to make the payments, you likely have repayment options.
1. Don’t ignore your Palm Beach Florida Mortgage Lender.
The further behind you become, the harder it will be to reinstate or modify your mortgage and the more likely that you will lose your house.
2. Contact your Palm Beach Florida mortgage lender as soon as you realize that you have a problem.
Palm Beach Florida mortgage lenders DO NOT want your house. They have options to help borrowers through difficult financial times.
3. Open and respond to all mail from your Palm Beach Florida mortgage lender.
The first notices you receive will offer good information about foreclosure prevention options that can help you weather financial problems. Later mail may include important notices of pending legal action. Your failure to open the mail will not be an excuse in foreclosure court.
4. Know your mortgage rights.
Find your loan documents and read them so you know what your lender may do if you can’t make your payments. Learn about the foreclosure laws and timeframes in your state (as every state is different) by contacting the State Government Housing Office.
5. Understand foreclosure prevention options.
Valuable information about foreclosure prevention (also called loss mitigation) options can be found online.
6. Contact a HUD-approved housing counselor.
The U.S. Department of Housing and Urban Development (HUD) funds free or very low-cost housing counseling nationwide. Housing counselors can help you understand the law and your options, organize your finances and represent you in negotiations with your lender, if you need this assistance. Find a HUD-approved housing counselor near you
7. Prioritize spending.
After healthcare, keeping your house should be your Number 1 priority. Review your income and expenses and see where you can cut spending. Look at canceling all unnecessary expenses that include eating out, cable TV, memberships, and entertainment that you can eliminate. Contact your credit cards to delay payments and other “unsecured” debt until you’re caught up on your mortgage payments.
8. Use your assets.
Do you have assets–a second car, jewelry, a whole life insurance policy–that you can sell for cash to help reinstate your loan? Can anyone in your household get an extra job to bring in additional income? Even if these efforts don’t significantly increase your available cash or your income, they demonstrate to your lender that you are willing to make sacrifices to keep your home.
9. Avoid foreclosure prevention companies.
You don’t need to pay fees for foreclosure prevention help–use that money to pay the mortgage instead. Many for-profit companies will contact you promising to negotiate with your lender. While these may be legitimate businesses, they will charge you a hefty fee (often two or three months’ mortgage payment) for information and services your lender or a HUD-approved housing counselor will provide free if you contact them.
10. Don’t lose your house to foreclosure recovery scams!
If any firm claims they can stop your foreclosure immediately and if you sign a document appointing them to act on your behalf, you may well be signing over the title to your property and becoming a renter in your own home! Never sign a legal document without reading and understanding all the terms and getting professional advice from an attorney, a trusted real estate professional or a HUD-approved housing counselor.
Few people think they will lose their home; they think they have more time.
Here’s how it happens. Note: Timeline varies by state.
- First month missed payment – your lender will contact you by letter or phone. A housing counselor can help.
- Second month missed payment – your lender is likely to begin calling you to discuss why you have not made your payments. It is important that you take their phone calls. Talk to your lender and explain your situation and what you are trying to do to resolve it. At this time, you still may be able to make one payment to prevent yourself from falling three months behind. A housing counselor can help.
- Third month missed payment after the third payment is missed, you will receive a letter from your lender stating the amount you are delinquent, and that you have 30 days to bring your mortgage current. This is called a “Demand Letter” or “Notice to Accelerate.” If you do not pay the specified amount or make some type of arrangements by the given date, the lender may begin foreclosure proceedings. They are unlikely to accept less than the total due without arrangements being made if you receive this letter. You still have time to work something out with your lender. A housing counselor can still help.
- Fourth month missed payment – now you are nearing the end of time allowed in your Demand or Notice to Accelerate Letter. When the 30 days ends, if you have not paid the full amount or worked our arrangements you will be referred to your lender’s attorneys. You will incur all attorney fees as part of your delinquency. A housing counselor can still help you.
- Sheriff’s or Public Trustee’s Sale – the attorney will schedule a Sale. This is the actual day of foreclosure. You may be notified of the date by mail, a notice is taped to your door, and the sale may be advertised in a local paper. The time between the Demand or Notice to Accelerate Letter and the actual Sale varies by state. In some states it can be as quick as 2-3 months. This is not the move-out date, but the end is near. You have until the date of sale to make arrangements with your lender, or pay the total amount owed, including attorney fees.
- Redemption Period – after the sale date, you may enter a redemption period. You will be notified of your time frame on the same notice that your state uses for your Sheriff’s or Public Trustee’s Sale.
Important: Stay in contact with your lender, and get assistance as early as possible. All dates are estimated and vary according to your state and your mortgage company.
Understand your rights.
Learn all that you can about your Palm Beach Florida mortgage rights and foreclosure laws. Review your loan documents to determine what your Flroida mortgage lender or servicer may do if you can’t make your payments. Review Palm Beach Florida laws, particularly Palm Beach Florida Statutes Chapter 702 to learn about foreclosure proceedings.
Contact a non-profit housing counselor.
Help and information are available to you free of cost. The HOPE NOW alliance provides a 24-hour hotline to provide mortgage counseling assistance in multiple languages. Reach this hotline by dialing, 1-888-995-HOPE. You may also obtain a list of U.S. Department of Housing and Urban Development (HUD) certified counselors in Palm Beach Florida here.
Understand the relevant terms.
If you are working with your mortgage servicer or an approved housing counselor to keep your home, there are several options:
- Reinstatement: Your servicer may agree to let you pay the total amount you are behind, in a lump sum payment and by a specific date. This is often combined with forbearance when you can show that funds from a bonus, tax refund or other source will become available at a specific time in the future. Be aware that there may be late fees and other costs associated with a reinstatement plan.
- Forbearance: Your servicer may offer a temporary reduction or suspension of your mortgage payments while you get back on your feet. Forbearance is often combined with a reinstatement or a repayment plan to pay off the missed or reduced mortgage payments. Please be aware that some forbearance plans require that you immediately pay back the missed payments in a lump sum at the end of the plan.
- Repayment Plan: This is an agreement that gives you a fixed amount of time to repay the amount you are behind by combining a portion of what is past due with your regular monthly payment. At the end of the repayment period you have gradually paid back the amount of your mortgage that was delinquent.
- Loan Modification: This is a written agreement between you and your mortgage servicer that permanently changes one or more of the original terms of your note to make the payments more affordable.
If you and your servicer agree that you cannot keep your home, there may still be options to avoid foreclosure:
- Short Payoff: If you can sell your house but the sale proceeds are less than the total amount you owe on your mortgage, your mortgage servicer may agree to a short payoff and write off the portion of your mortgage that exceeds the net proceeds from the sale.
- Deed-in-Lieu of Foreclosure: A deed-in-lieu of foreclosure is a cancellation of your mortgage if you voluntarily transfer title of your property to your mortgage servicer. Usually you must try to sell your home for its fair market value for at least 90 days before a mortgage company will consider this option. A deed-in-lieu of foreclosure may not be an option if there are other liens on the property, such as second mortgages, judgments from creditors or tax liens.
- Assumption: An assumption permits a qualified buyer to take over your mortgage debt and make the mortgage payments, even if the mortgage is non-assumable. As a result, you may be able to sell your property and avoid foreclosure.
- ReStop Foreclosure mortgage refinancing : While reStop Foreclosure mortgage refinancing is not necessarily a good option when facing foreclosure and can sometimes even be a predatory practice, there are instances where it may help. Talk to your servicer to see if reStop Foreclosure mortgage refinancing is an option for you.
Carefully examine your finances.
Can you cut spending on optional expenses or delay payments on credit cards or other unsecured debt until you have paid your mortgage? Do you have assets that you could sell to help reinstate your loan? Can anyone in the household get a second job to help with income? These efforts to manage your finances may help you find income to apply to your outstanding payments and will demonstrate to your servicer that you are willing to work on your finances and make sacrifices in order to keep your home.
Do not fall victim to a foreclosure recovery scam.
If any business or individual offers to help you stop foreclosure immediately by signing a document authorizing them to act on your behalf or to set up Stop Foreclosure mortgage refinancing , do not sign without consulting a professional (an attorney or HUD-approved counselor). This may be a trick to get you to sign over title to your home. You are then vulnerable to losing your home and all of your equity in your home to the so-called rescuer.
The Consumer Financial Protection Bureau also provides useful information in avoiding scams. You can access the CFPB’s website on how to avoid foreclosure rescue scams here.
Avoid for-profit foreclosure prevention or loss mitigation companies.
If you fall behind in your mortgage payments, many for-profit companies will contact you promising to help you avoid foreclosure. Some may even appear to be affiliated with your lender or servicer. It is best to avoid dealing with these companies. Most will charge you a hefty fee up front for information that your servicer or a HUD-approved counselor will provide for free. You can obtain the same plan or a better plan for free by contacting your servicer or a HUD-approved counselor. Use your money to pay the mortgage instead.
Should you require outside resources to avoid foreclosure, seek out a licensed mortgage broker or an attorney. You can verify a mortgage broker’s license on the Office of Financial Regulation’s website. A rescue firm or mortgage broker may never charge you up front. They may only charge you after you receive and accept a written offer for a loan or refinance contract.
494.00794 Right to cure high-cost Palm Beach Florida home loans
(2) GROUNDS FOR REINSTATEMENT.Palm Beach Florida Business Refinance Before any action filed to foreclose upon the home or other action is taken to seize or transfer ownership of the home, a notice of the right to cure the default must be delivered to the borrower at the address of the property upon which any security exists for the home loan by postage prepaid certified United States mail, return receipt requested, which notice is effective upon deposit in the United States mail, and shall inform the borrower:
Palm Beach Florida Stop Foreclosure Information
- What to Do When Facing Foreclosure (online video)
- NeighborWorks America
- FloridaLawHelp.org
- Resources Available to Distressed Homeowners (brochure), Office of the Attorney General of Florida
- The Legal Aid Society of Palm Beach County, Inc. – Fair Housing Project: Foreclosure Defense Unit
- Avoiding Foreclosure (HUD)
Palm Beach Florida Stop Foreclosure Legal Help
- Foreclosure Defense Unit, Legal Aid Society of Palm Beach County
- Call: 561-655-8944, Ext. 325
- Email: foreclosuredefenseunit@legalaidpbc.org
- Lawyer Referral Service
- Palm Beach County Bar Association, or Call: 561-687-3266
- Clerk of the Circuit Court & Comptroller’s Self-Service Centers
Palm Beach Florida Stop Foreclosure Counseling Services
- HUD Approved Housing Counseling Agencies
- U.S. Department of Housing and Urban Development
- Homeowner’s HOPE™ Hotline (24/7 Advice): 888-995-HOPE (4673), 24-hour phone line
Avoiding Foreclosure Palm Beach Florida
- Federal Trade Commission
- Avoiding Foreclosure
- U.S. Department of Housing and Urban Development
- Avoid Foreclosure: Know Your Options (online video)
- Save Your Home: Tips to Avoid Foreclosure (brochure)
- Federal Housing Administration, HUD
- How to Protect Yourself: Tips for Avoiding Mortgage Foreclosures
- Attorney General of Florida
- Department of the Treasury
- Reverse Mortgages: Get the Facts Before Cashing in on Your Home’s Equity
Protect Yourself From Scams
- Mortgage Fraud
- Office of the Attorney General of Florida
- Report Mortgage Fraud or Loan Scams
- Florida Attorney General’s Fraud Hotline: 866-9-NO-SCAM